For Non-Resident Indians (NRIs), buying property in India is one of the most emotional and significant investment decisions. Whether for family, retirement, rental income or long-term wealth preservation, Indian real estate remains a key allocation. But rules under FEMA (Foreign Exchange Management Act) govern what NRIs / OCIs can and cannot buy - and the process involves specific documentation.
This 2026 guide covers everything: FEMA rules, permitted property types, NRI home loans, TDS on purchase, Form 15CA/CB, Power of Attorney and best Indian cities for NRI property investment.
FEMA rules on NRI property purchase, TDS Section 194-IA and Section 195, and RBI Master Direction on Acquisition of Immovable Property in India are established provisions. Verify current rules at rbi.org.in and consult a qualified CA + real-estate lawyer before purchase.
FEMA - What NRIs and OCIs CAN Buy
- Residential property (apartments, villas, plots for residential purpose)
- Commercial property (offices, shops, retail spaces, warehouses)
- Multiple residential + commercial properties (no upper limit)
- Property inherited (as gift or through succession)
FEMA - What NRIs and OCIs CANNOT Buy
- Agricultural land (freshly purchased - inherited agricultural land can be retained)
- Plantation property
- Farm houses (unless converted to non-agricultural residential zone)
Violation of FEMA agricultural-land rule can trigger fines up to 3x property value + confiscation.
Approved Funding Sources
Payment for NRI property purchase must be via:
- NRE account (repatriable route - highest flexibility)
- NRO account (non-repatriable / capped repatriation)
- FCNR(B) account
- Direct inward remittance from overseas via SWIFT / Wise / Remitly
Cash payment strictly prohibited beyond ₹2 lakh per transaction (Section 269SS).
TDS on NRI Property Purchase - Two Sections
Section 194-IA - If Buying From Resident Seller
You (buyer NRI) deduct 1% TDS on property value if consideration exceeds ₹50 lakh. You are the deductor here.
Section 195 - If Buying From Another NRI Seller
You (buyer) deduct 20-30% TDS (depending on holding period + capital gains type) on payment to the seller. You are the deductor.
- LTCG (held >24 months): 20% TDS on total consideration (default)
- STCG (held <24 months): 30% TDS
- Reduce TDS via Section 197 lower-deduction certificate or Section 195(2) ITO permission
If you're the buyer, apply for a TAN before deducting TDS.
Home Loan Options for NRIs
All major Indian banks offer NRI home loans:
- HDFC Bank - up to 80% LTV, 15-year tenure typical (up to 20 years for salaried NRI)
- ICICI Bank - similar terms, strong NRI banking relationship required
- SBI - government-backing, competitive rates, wide branch network in India
- Kotak Mahindra, Axis Bank, IndusInd - premium NRI service
- LIC Housing Finance, PNB Housing - specialised home-finance NBFCs
Typical NRI Home Loan Terms 2026
- Interest rates: ~8.5-9.5% (variable based on RBI repo rate + spread)
- Tenure: Up to 15-20 years (max age at loan closure typically 60-65)
- LTV: Up to 80% (some banks 90% for existing customers)
- Processing fee: 0.5-1% of loan amount
- Repayment: EMI via NRE/NRO account debit
- Guarantor: sometimes required (Indian resident co-applicant)
Power of Attorney (POA) for Remote NRIs
Most NRIs cannot travel repeatedly for property paperwork. A Power of Attorney to a trusted resident-Indian (parent, sibling, close relative) enables them to sign documents on your behalf.
POA Types
- General Power of Attorney (GPA): broad powers - avoid for property (Supreme Court 2011 ruling limits GPA-based property title)
- Special Power of Attorney (SPA): specific-purpose (recommended for property transactions)
- Registered POA: Sub-registrar office (mandatory for property registration)
POA Attestation Process
- Draft POA in India with lawyer
- Send draft to NRI abroad
- NRI signs in presence of Indian consulate officer (attestation)
- Send back to India
- Adjudication + stamp duty payment in India
- Registration at Sub-Registrar office
Documents Required for NRI Property Purchase
- Original passport + foreign visa/OCI/PIO card
- PAN card (mandatory for property transactions > ₹10 lakh)
- Overseas address proof
- Salary slip + tax returns (for loan approval)
- Bank statements (6 months)
- Property agreement copy
- Sale deed of seller
- Encumbrance certificate
- Property tax receipts (last 3 years)
- Approved building plan
- Occupancy certificate (for completed projects)
- Society NOC (for resale/apartment)
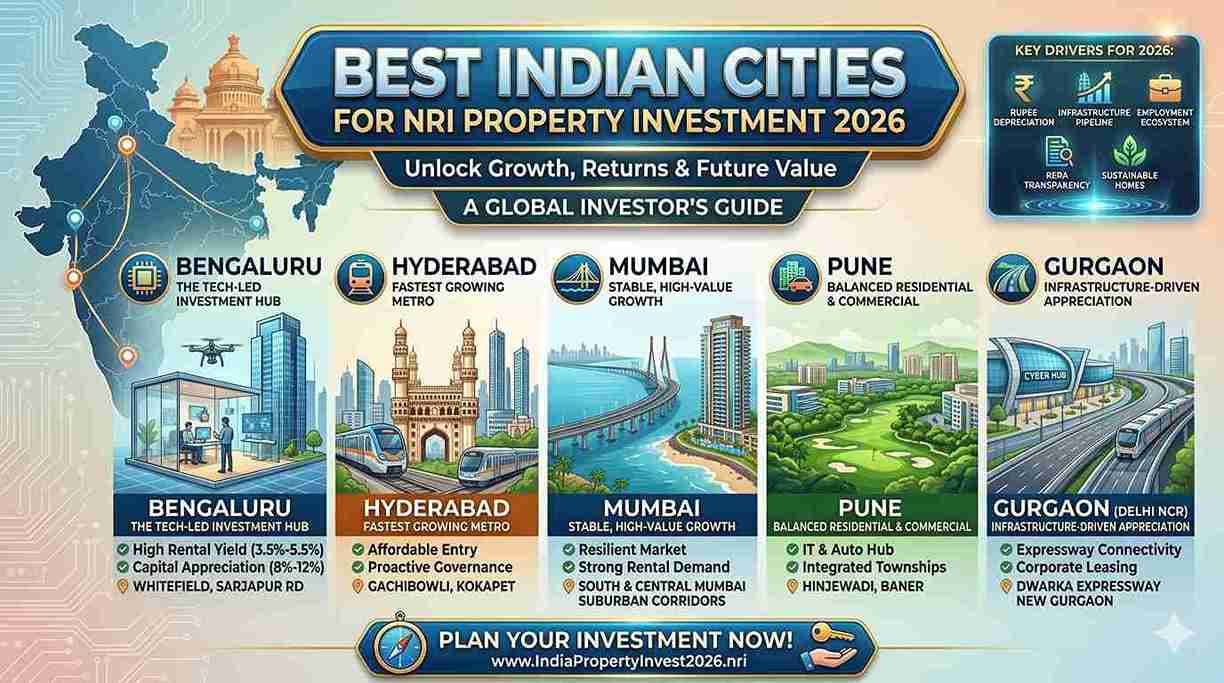
Best Indian Cities for NRI Property Investment 2026
- Bangalore: IT hub, high rental yields (3-4%), strong appreciation potential
- Hyderabad: emerging tech hub, more affordable than Bangalore
- Mumbai (western suburbs, Navi Mumbai): commercial capital, high entry cost but stable
- Pune: education + IT hub, growth corridor
- Chennai (OMR, ECR): IT hub, coastal appeal
- Gurgaon / Noida: corporate hub for North India NRI investment
- Kochi (Ernakulam): highest concentration of Kerala NRI capital
- Kolkata (Rajarhat): emerging affordable option
- Ahmedabad (SG Highway): growing corporate hub
Step-by-Step NRI Property Purchase Process
- Set NRI banking + PAN - open NRE + PIS demat if needed
- Shortlist properties - visit personally or via trusted family member
- Legal due diligence - hire property lawyer to verify title, encumbrance
- Home loan pre-approval if financing
- Token/booking amount via NRE cheque
- Draft sale agreement - lawyer review
- TDS deduction and payment (Section 194-IA if resident seller)
- Final payment + registration at Sub-Registrar office
- Stamp duty + registration fees (5-8% depending on state)
- Society/RERA NOC + name transfer
- Property tax + utility mutations
Post-Purchase Compliance
- Report to Indian Income Tax Department via ITR-2 (Section 6 - immovable property purchase disclosure)
- US NRIs: report property on FBAR + Form 8938 if applicable
- Set up rent collection via NRO account
- Maintain municipal + society records for future sale/inheritance
- Property insurance (highly recommended - Bharat Griha Raksha for burglary + fire cover)
FAQ
Can NRIs buy property in India without visiting?
Yes - via Power of Attorney to a trusted resident-Indian. POA must be attested at Indian consulate abroad and registered at Sub-Registrar in India.
Is loan approval faster for NRIs?
Not necessarily - can take 4-8 weeks. Documentation more extensive due to overseas verification requirements.
What is the maximum property value an NRI can buy?
No upper limit under FEMA. Multiple properties allowed.
Can NRI parents buy property jointly with children?
Yes if children are Indian residents or NRIs. Foreign nationals (non-OCI) cannot co-own except as inherited beneficiary.
What is Section 194-IA TDS?
1% TDS deducted by buyer when purchasing property from resident seller and consideration exceeds ₹50 lakh. Deposit to IT Dept via Form 26QB.
Can I use NRE funds for down payment and NRO for EMI?
Yes - purchase can be from either NRE or NRO. EMI on home loan can be paid from either. If from NRE, EMI is fully repatriable-linked.
Trusted Sources
- RBI.org.in - FEMA Master Direction on Acquisition of Immovable Property
- Incometax.gov.in - TDS provisions Sections 194-IA and 195, Form 26QB
- RERA (Real Estate Regulatory Authority) state portals for project verification
- Your qualified property lawyer + CA in India
Related NRI Globe Coverage
- NRI Property Selling in India 2026
- NRE vs NRO Tax Comparison
- FEMA NRO Transfer Rules
- NRI Investment Options 2026
Disclaimer: Informational only. FEMA rules + TDS rates + state stamp-duty rates change. Verify current rules at rbi.org.in and consult qualified real-estate lawyer + CA before purchase.
More NRI Globe Coverage For You
- NRI Property in India 2026: What You Can Buy, FEMA Rules, Inheritance and the Agricultural-Land Question
- NRI Guide to Buying Property in India: Legal & Tax Tips for 2025
- NRI Property Sale in India 2026: Tax, TDS & Repatriation Guide
- Buying vs. Renting Property in India as an NRI: 2025 Guide
- India Real Estate NRI Compliance Guide 2026 — FEMA, RBI, Tax, TDS, Repatriation Rules
- NRI Investment India 2026 — Mutual Funds, Property, FD, NRE/NRO Complete Pillar
- FEMA Rules for NRO Account Transfers 2026 - Complete NRI Guide (USD 1M Repatriation, Form 145/146, Source Proof)
- NRE Account Repatriation Limits 2026 - Complete NRI Guide (No FEMA Limit, Free Transfer Process, Form A2, SWIFT)
- Bathukamma Celebrations in Dubai & UAE 2026 - Complete NRI Guide (ETCA, GTF, Telugu Association UAE, Abu Dhabi Telangana Friends)
- Bathukamma Celebrations in Australia 2026 - Complete NRI Guide (Sydney, Melbourne, Brisbane, Townsville - TAQ, ATAI, Melbourne Telangana Forum)
- Bathukamma Celebrations in UK 2026 - Complete NRI Guide (London, Birmingham, Scotland, Manchester - TAUK, TCUK Mega Bathukamma Southend Oct 17)
- Bathukamma Celebrations in Canada 2026 - Complete NRI Guide (Toronto, Brampton, Vancouver, Calgary, Edmonton - TDF Canada, TCA)