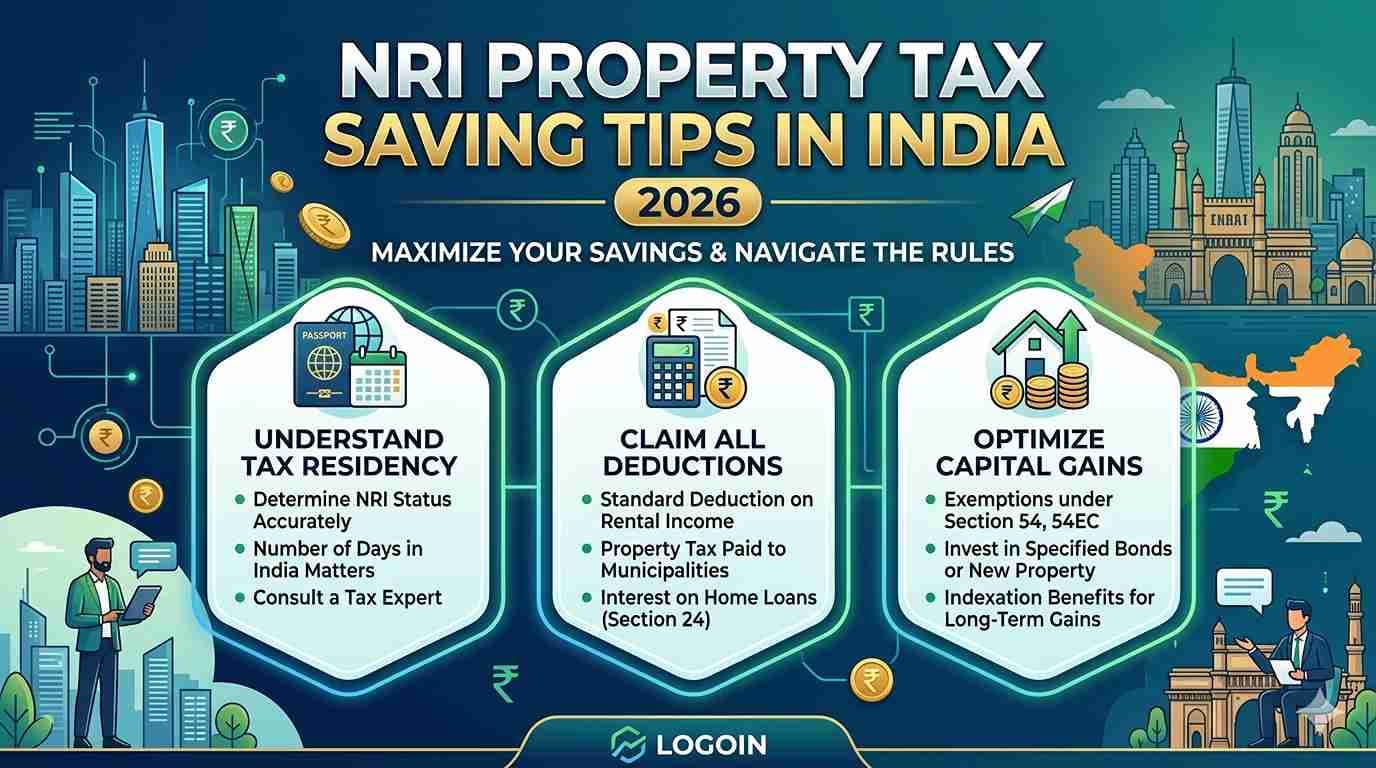
Selling property in India as an NRI is significantly more complex than for resident sellers. Buyers must deduct 20-30% TDS under Section 195 (not 1% Section 194-IA that applies for resident sellers), often creating short-term liquidity issues even when your actual capital gains are much lower.
This 2026 guide covers TDS calculation, LTCG rules, Section 54/54F/54EC exemptions to reinvest and defer/eliminate tax, Section 197 lower-deduction certificate, Form 15CA/15CB documentation and USD 1 million repatriation.
Section 195 TDS, Section 54/54F/54EC exemptions, Section 197 lower-deduction, Form 15CA/15CB and FEMA repatriation cap are established Income Tax Act + RBI rules. Verify current rates + forms at incometax.gov.in and rbi.org.in before filing.
The Critical Difference: Sec 194-IA vs Sec 195
| Aspect | Section 194-IA (Resident Seller) | Section 195 (NRI Seller) |
|---|---|---|
| Applies to | Buyer of property from resident | Buyer of property from NRI |
| Threshold | Consideration > ₹50 lakh | Any amount |
| TDS Rate | 1% of consideration | 20% LTCG / 30% STCG on total consideration (default) |
| Base | Sale value | Sale value (unless Section 197 certificate) |
| Form | Form 26QB | Form 27Q |
| Buyer's TAN | Not required | Required |
Critical: The 20-30% TDS is on the FULL sale value, not just the capital gain. If you sell a ₹1 crore property with only ₹30 lakh gain, TDS is still ₹20 lakh unless you get a lower-deduction certificate.
Capital Gains Calculation
Long-Term Capital Gain (LTCG)
Property held > 24 months (2 years) qualifies as long-term:
- Rate: 20% + surcharge + 4% cess
- Indexation benefit applies (Cost Inflation Index - CII)
- LTCG = Sale Price - Indexed Cost of Acquisition - Indexed Cost of Improvement - Transfer Expenses
Short-Term Capital Gain (STCG)
Property held < 24 months:
- Rate: Slab rates for NRI (typically 30% + surcharge + cess)
- No indexation benefit
- STCG = Sale Price - Cost of Acquisition - Cost of Improvement - Transfer Expenses
LTCG Exemptions - Reinvest to Save Tax
Section 54 - Buy Another Residential Property
- Applicable if selling residential property
- Reinvest LTCG in another residential property in India
- New purchase: within 1 year before or 2 years after sale
- Construction: within 3 years
- Only 1 residential property purchase allowed (exception: LTCG < ₹2 crore + one-time - 2 properties)
- Deposit unutilised amount in Capital Gains Account Scheme (CGAS) before ITR due date
Section 54F - Sell Any Long-Term Asset, Buy Residential
- Applicable if selling non-residential long-term asset (equity, gold, plot) and buying residential property
- Full LTCG exempt if entire sale proceeds reinvested in one residential property
- Proportionate exemption if partial reinvestment
- Must not own more than 1 house on date of sale (excluding new one)
Section 54EC - Invest in Specified Bonds
- Reinvest LTCG in bonds of NHAI, REC, PFC, IRFC etc.
- Maximum ₹50 lakh per FY (across all Sec 54EC bonds)
- Lock-in: 5 years
- Interest ~5-5.5% taxable
- Invest within 6 months of sale date
Section 197 Lower-Deduction Certificate
This is the KEY tool to avoid excess TDS. Apply for a certificate authorising lower or nil TDS deduction on your actual estimated capital gain:
- Apply before property sale via Form 13 on incometax.gov.in
- ITO (Income Tax Officer) issues certificate specifying reduced TDS rate/nil rate
- Share certificate with buyer
- Buyer deducts TDS as per certificate (e.g., 5% instead of 20%)
- Timeline: 4-6 weeks typically
Repatriation of Sale Proceeds - USD 1 Million Cap
Post-tax sale proceeds go to NRO account. To repatriate abroad:
USD 1 Million Annual Cap Applies
- Sale of up to 2 residential properties (original investment amount) can be repatriated additionally
- Beyond that, all NRO outward remittances covered by USD 1 million annual cap
- Form 15CA + Form 15CB (CA certificate) required
Form 15CA/CB Process
- Chartered Accountant issues Form 15CB certifying tax compliance
- File Form 15CA online at incometax.gov.in
- Submit to bank
- Bank processes SWIFT transfer
Documents Required for NRI Property Sale
- Sale agreement + registered sale deed
- Property title documents (parent + subsequent)
- Encumbrance certificate (latest)
- Property tax paid receipts
- Society NOC
- Approved building plan + occupancy certificate
- Passport + PAN
- Original purchase deed with cost of acquisition proof
- Improvement bills (for cost-of-improvement claim)
- Section 197 lower-deduction certificate (if obtained)
Step-by-Step NRI Property Sale Process
- List property via broker or online portal (99acres, MagicBricks, NoBroker)
- Legal due diligence - verify property title + encumbrance is clear
- Estimate capital gain with CA
- Apply for Section 197 certificate if TDS will be more than actual tax
- Negotiate + finalise buyer
- Draft sale agreement - lawyer review
- Token amount via bank draft
- Buyer applies for TAN (mandatory for Section 195 TDS deduction)
- Buyer deducts TDS + deposits to IT Dept (Form 27Q)
- Final payment + registration at Sub-Registrar
- Update PAN records - Section 6 disclosure
- File ITR-2 in India to reconcile TDS vs actual tax; claim refund if applicable
- Form 15CA + Form 15CB for repatriation
- Wire funds abroad from NRO account (within USD 1M cap)
US-Based NRI - Additional Considerations
- Report Indian property sale on US Form 8949 + Schedule D
- Claim Foreign Tax Credit on Form 1116 for India TDS
- US LTCG rates: 0%/15%/20% (federal) - depending on income bracket
- Also state tax applicable (varies)
- Section 54/54F/54EC exemption in India may not have US equivalent - full US tax still due on gain
Common Mistakes to Avoid
- Assuming buyer will deduct only 1% TDS (Sec 194-IA) when actually 20% (Sec 195) applies
- Not applying for Section 197 certificate - massive over-deduction
- Missing Form 15CA/15CB for repatriation
- Not investing in Sec 54/54F/54EC in time (specific window)
- Failing to deposit Sec 54 unutilised amount in CGAS before ITR due date
- Not claiming DTAA relief in US (missing Foreign Tax Credit)
- Confusing NRO 1M repatriation cap with property-specific 2-property allowance
FAQ
What TDS applies when NRI sells property?
20% + surcharge + cess (LTCG) or 30% + surcharge + cess (STCG) under Section 195. Applied on TOTAL sale value, not just capital gain, unless Section 197 lower-deduction certificate obtained.
How can NRIs reduce TDS on property sale?
Apply for Section 197 lower-deduction certificate (Form 13) BEFORE sale. ITO issues certificate specifying reduced rate based on actual estimated capital gain. Share with buyer.
Can I reinvest and save tax on property sale?
Yes - Section 54 (residential to residential), Section 54F (any long-term to residential), Section 54EC (LTCG in specified bonds, max ₹50L). Each has specific conditions.
How much can NRI repatriate from property sale?
Original investment amount of up to 2 residential properties + USD 1 million annual cap for balance.
Do I need TAN if I buy from NRI?
Yes - buyer must obtain TAN (via Form 49B) before deducting TDS under Section 195.
Is Section 194-IA 1% TDS applicable when NRI sells?
NO. Section 194-IA applies only when SELLER is resident Indian. NRI seller triggers Section 195 (20-30% TDS).
Trusted Sources
- Incometax.gov.in - Section 195, 197, 54/54F/54EC, ITR-2 filing
- RBI.org.in - FEMA repatriation rules
- Your qualified CA + property lawyer - essential for complex transactions
Related NRI Globe Coverage
Disclaimer: Informational only. Tax rates + FEMA rules + exemption conditions change - verify at incometax.gov.in and rbi.org.in. Consult qualified CA + property lawyer BEFORE listing property for sale.
More NRI Globe Coverage For You
- NRI Property Buying in India 2026 - Complete Guide (FEMA Rules, Home Loan, Agricultural Land Ban, TDS, Form 15CA/CB, Power of Attorney)
- NRI Selling Indian Property Step-by-Step in 2026: TDS, Capital Gains, Section 197, Repatriation
- NRI Property Sale in India 2026: Tax, TDS & Repatriation Guide
- NRI Guide to Buying Property in India: Legal & Tax Tips for 2025
- NRI Investment India 2026 — Mutual Funds, Property, FD, NRE/NRO Complete Pillar
- NRI Property in India 2026: What You Can Buy, FEMA Rules, Inheritance and the Agricultural-Land Question
- Buying vs. Renting Property in India as an NRI: 2025 Guide
- US-India DTAA Complete Guide 2026 - TRC + Form 10F, Tax Residency, Foreign Tax Credit (Form 1116), Treaty Rates on Dividend/Interest/Salary
- Bathukamma Celebrations in Dubai & UAE 2026 - Complete NRI Guide (ETCA, GTF, Telugu Association UAE, Abu Dhabi Telangana Friends)
- Bathukamma Celebrations in Australia 2026 - Complete NRI Guide (Sydney, Melbourne, Brisbane, Townsville - TAQ, ATAI, Melbourne Telangana Forum)
- Bathukamma Celebrations in UK 2026 - Complete NRI Guide (London, Birmingham, Scotland, Manchester - TAUK, TCUK Mega Bathukamma Southend Oct 17)
- Bathukamma Celebrations in Canada 2026 - Complete NRI Guide (Toronto, Brampton, Vancouver, Calgary, Edmonton - TDF Canada, TCA)